

If you are short on time:
Barcelona remains one of Spain’s most important student markets, with enrolment continuing to grow and international students playing an increasingly important role in supporting demand.
Private PBSA supply has expanded rapidly, driven by the continued growth of established operators such as Yugo and aparto Student, alongside new entrants including Amro Estudiantes. Even so, the market remains far from saturated.
The latest development wave has become increasingly concentrated around Barcelona’s main higher education clusters, particularly around Universitat de Barcelona and Universitat Politècnica de Catalunya.
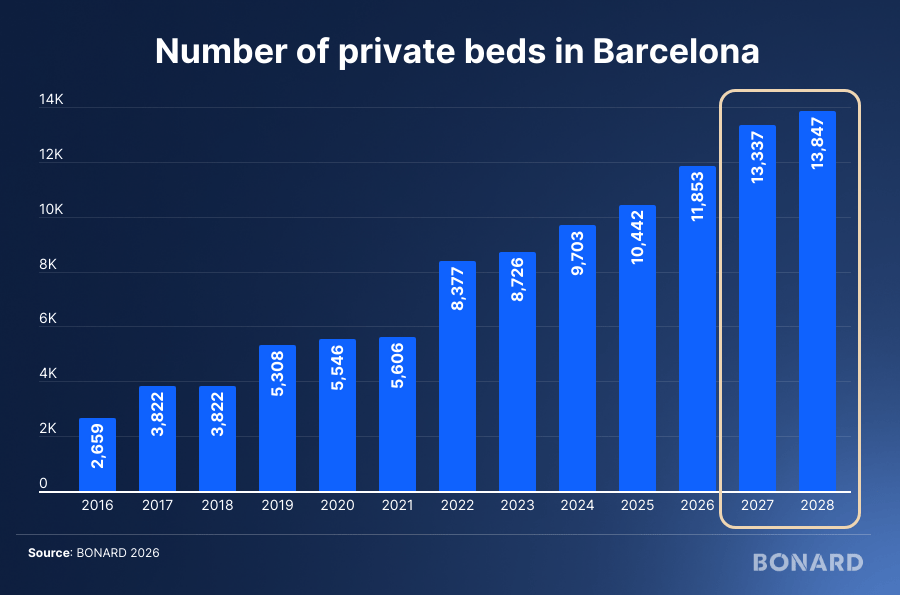
Barcelona, the second largest student hub in Spain, has added private student accommodation at a remarkable pace, private PBSA capacity more than quadrupled over the past 10 years. For new schemes broadening the market developer place greater emphasis on strategic locations and carefully calibrated product offerings to deliver accommodation that is both competitive and commercially viable.
Barcelona’s PBSA market is also beginning to demonstrate greater transactional depth along with continued institutionalisation of the market. Ardian and Rockfield acquired the 750‑bed Aparto Pallars in the 22@ district in late 2025, while Azora acquired the 610‑room Alba Viu residence in Cerdanyola del Vallès. These recent acquisitions of stabilised assets suggest that investor interest is extending beyond development opportunities into operational stock.
Yet, despite this wave of development, the city's net provision rate remains low at just 17.5%.
Demand continues to outpace rapidly expanding delivery of PBSA beds
Barcelona continues to reinforce its position as one of Southern Europe’s leading higher education destinations, underpinned by a globally recognised university ecosystem, an expanding range of English‑taught programmes, and the international standing of institutions such as Universitat de Barcelona, Universitat Autònoma de Barcelona and Pompeu Fabra University. The city’s strong international connectivity, diversified economy and growing strength in STEM, healthcare, technology and business‑related disciplines further enhance its appeal to both EU and non‑EU students.
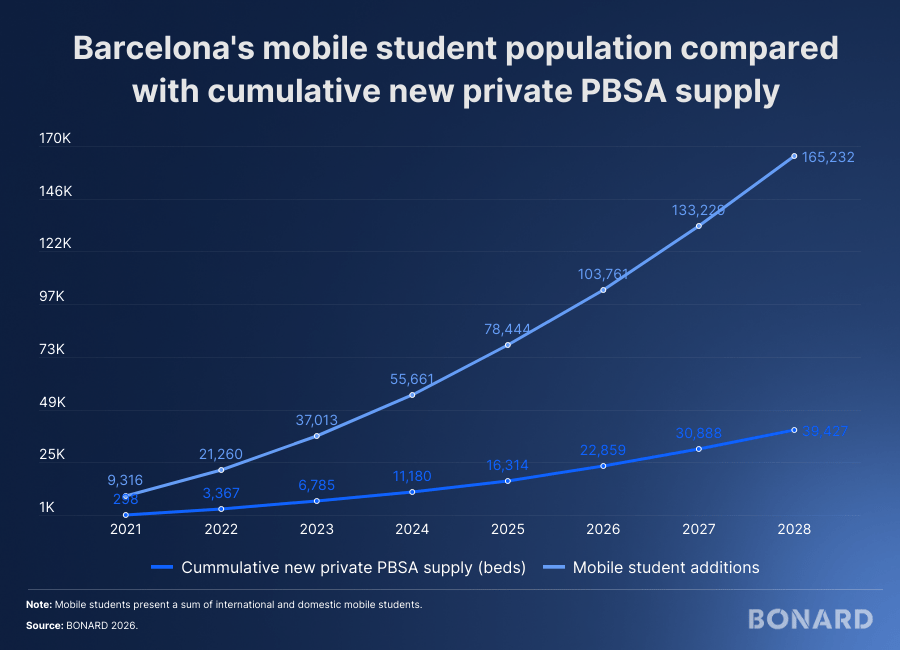
Against this backdrop, the mobile student population – comprising both international and domestic students studying away from home – continues to grow faster than the supplyof dedicated student accommodation, sustaining pressure on the housing market.
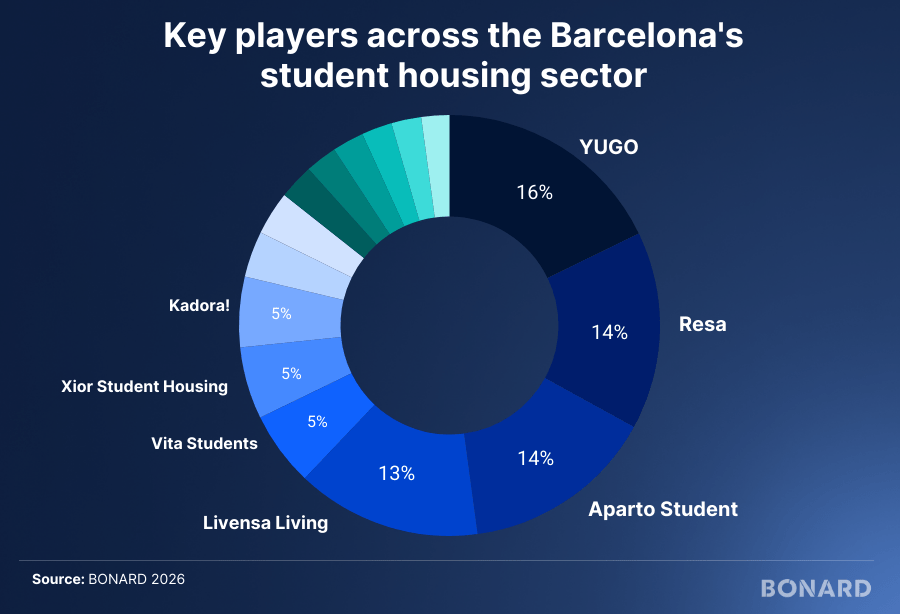
Barcelona has added private student accommodation at a remarkable pace, private PBSA capacity more than quadrupled over the past 10 years. Resa was one of the earliest operators to establish a sizeable branded student‑housing platform in Barcelona, with the company already firmly established in the city by the mid‑2010s. Since then, Barcelona’s PBSA landscape has become considerably more diverse and international.
Yugo, aparto and Livensa Living have all expanded their presence over the past decade and today account for more than 5,000 beds between them, highlighting the rapid institutionalisation of a market that was once dominated by a relatively small number of established providers.
The recent wave of PBSA development has largely followed Barcelona’s main higher education clusters, with Universitat de Barcelona and Universitat Politècnica de Catalunya attracting the greatest concentration of new schemes.
Investor and operator interest shows little sign of fading. Established players continue to expand, with Resa preparing a new 510‑bed residence at Vall d’Hebron for the 2027/28 academic year, while micampus is bringing its first residence in Barcelona city to the market at Meridiana. At the same time, new names are entering the purpose‑built segment: Amro is developing a 400‑bed scheme in Cerdanyola, scheduled for completion in 2027, while Mi Casa Inn, already active in Barcelona through student apartments, is advertising its first dedicated Barcelona student residence as “coming soon”.
What does this mean for stakeholders?
Barcelona is Spain’s second largest student hub and continues to benefit from growing student demand, increasingly driven by international enrolment.
Private PBSA supply has expanded rapidly in recent years, supported by the entry and expansion of institutional operators, but yet provision remains low. Development has increasingly clustered around the city’s major university hubs, while the product is evolving itself: after a period characterised by amenity‑rich schemes, the market is now placing greater emphasis on affordability, operational efficiency and amenities that deliver genuine value to students.
"Beyond sheer volume growth, investor strategy has shifted toward acquiring operational stock, while new developments have evolved from amenity‑heavy concepts to affordable, operationally efficient schemes clustered around major university hubs."
Ina Durcekova
Real Estate Consultant, BONARD
Explore student housing market in greater depth on theBONARD Platform, or contact Filip for tailored guidance on your next acquisition or development strategy.
SUBSCRIBE TO STUDENT HOUSING INSIDER
Stay close to the student housing market
Subscribe to Student Housing Insider for a weekly update on student housing transactions, development pipeline, market trends and selected BONARD analysis.
Designed for investors, developers, operators, lenders and market participants tracking the student housing sector.